
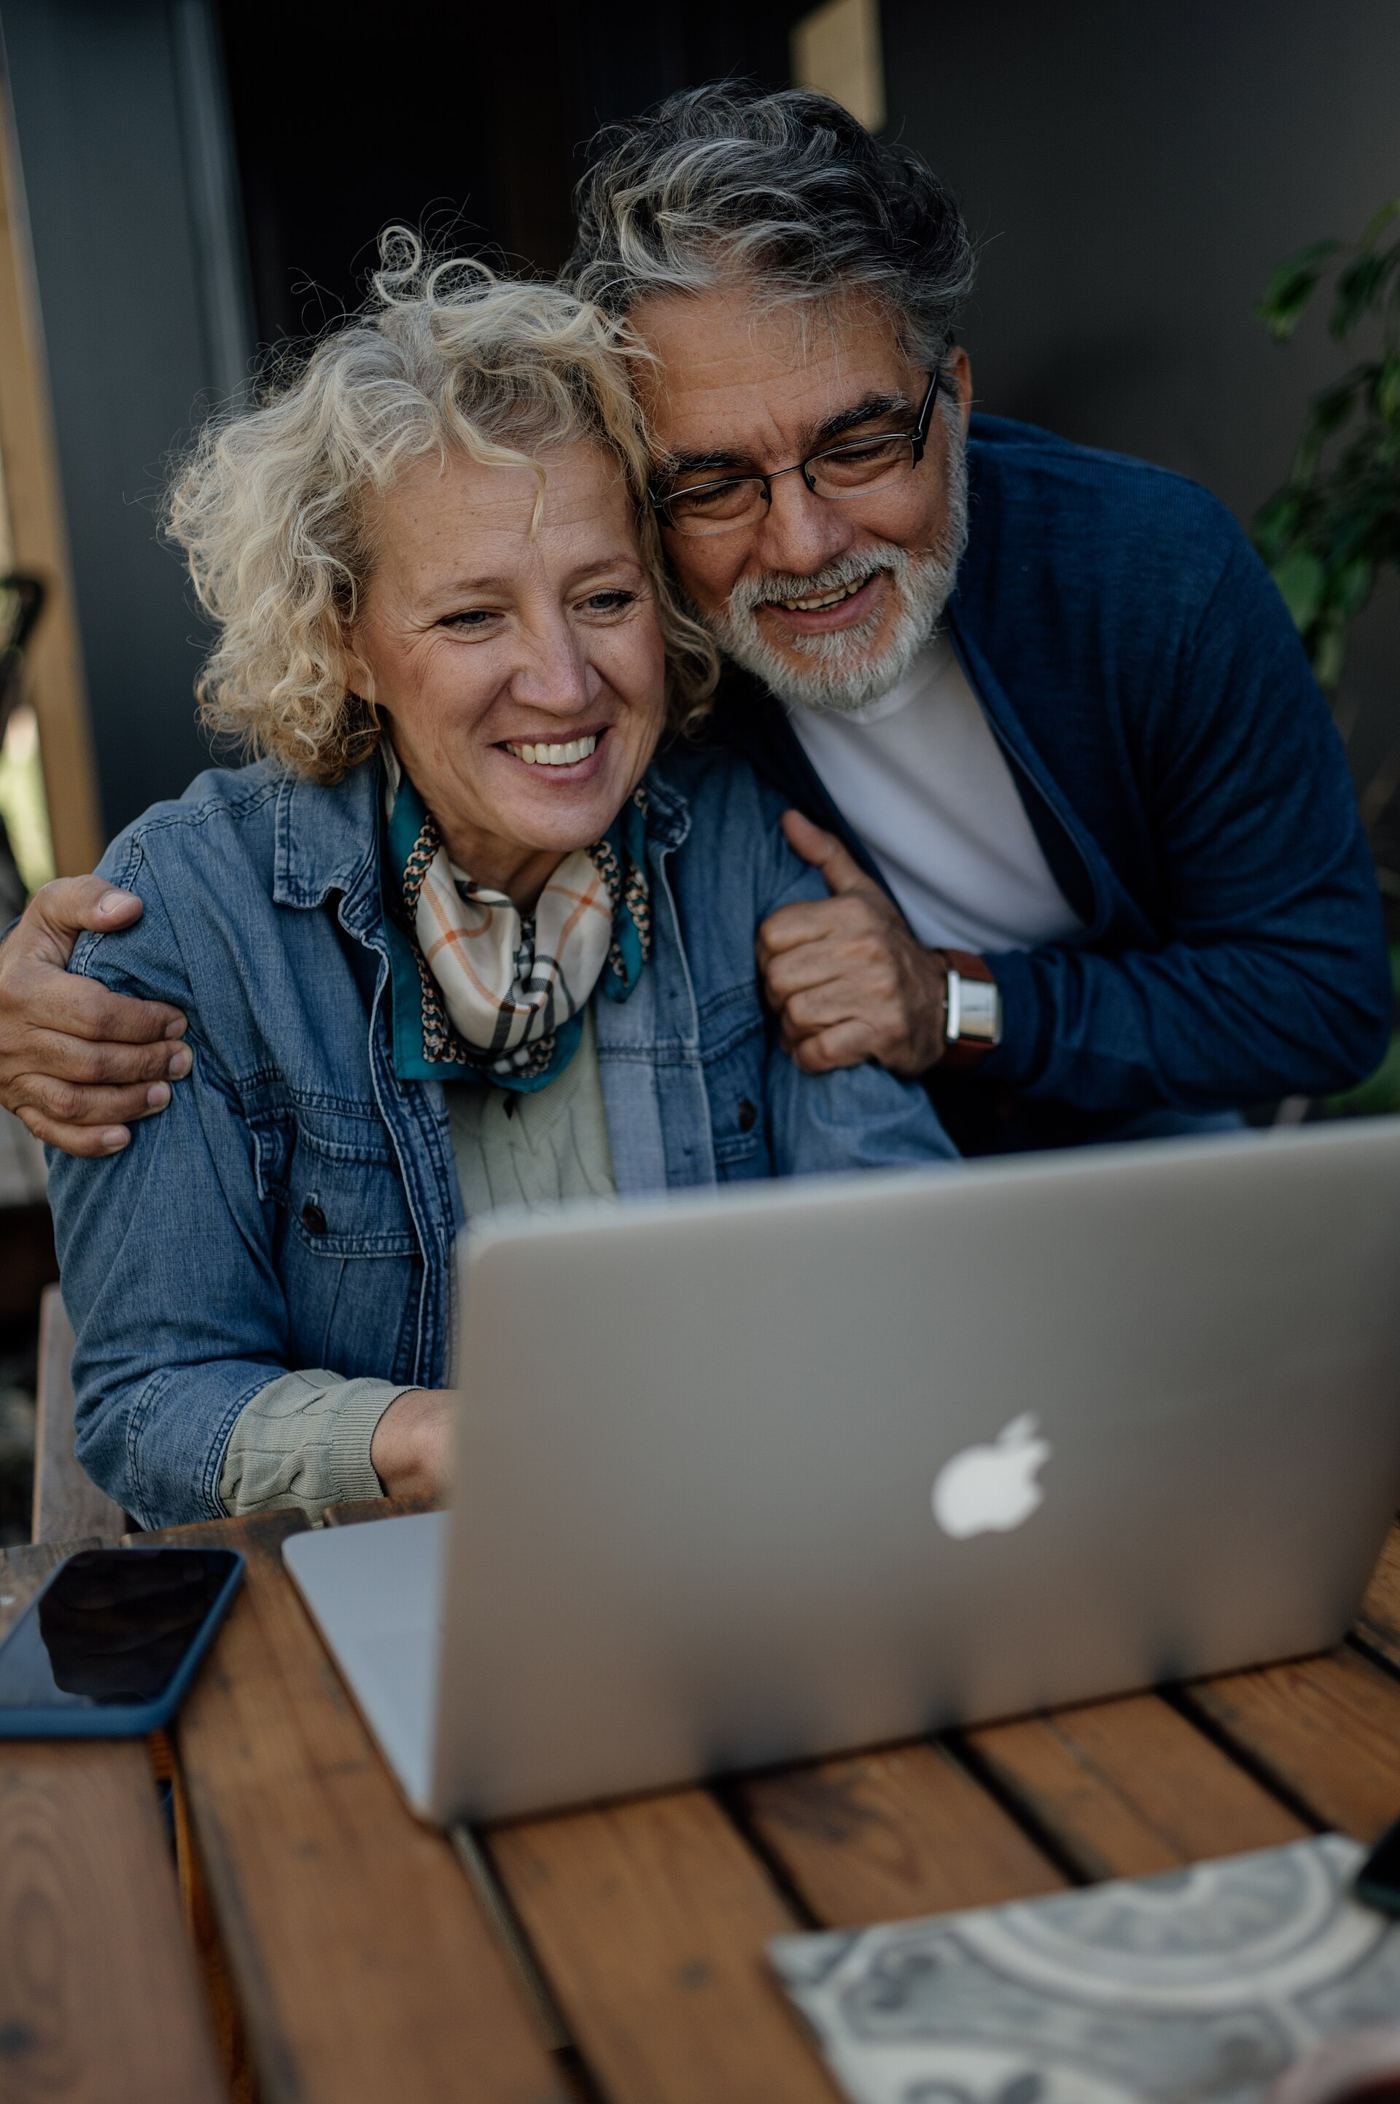
Workers in their fifties are being urged to review their retirement plans earlier and more carefully, as longer lives, changing pension rules and higher living costs make last minute decisions increasingly risky. A proper review starts with gathering every pension statement, savings account and debt into one clear picture, something many people postpone because the paperwork feels overwhelming. Advisers say the exercise is usually reassuring, because people often discover small pensions from earlier jobs and gain a realistic sense of what their retirement income could look like. Knowing the numbers early creates options, from increasing contributions gradually to adjusting retirement dates, rather than facing unwelcome surprises at sixty five. Workplace pension workshops and free guidance services can help people start the process without paying for full advice immediately.
What the Evidence Shows
Key questions include when to claim state benefits, how to sequence withdrawals tax efficiently and whether housing costs will fall, stay steady or rise in later life. Couples should plan together, considering different retirement dates, health needs and the income that would remain for a surviving partner. Advisers also warn against making irreversible decisions during market volatility, when pension values shown on a statement may recover within months. Annual reviews keep plans aligned with changing rules, family circumstances and personal goals such as travel, part time work or helping children financially. Retirement planning is rarely finished in one afternoon, but a documented, regularly updated plan gives people confidence and control over a major life transition. Keeping copies organised in one folder, digital or paper, makes each future review quicker and far less stressful. Reporting and analysis from sources such as Financial Times track the same developments, and specialists following earlier retirement planning in your fifties say the direction is now consistent across independent lines of evidence.
The Wider Context
The wider context is a financial system repricing risk after a long era of cheap money. Decisions shaped by earlier retirement planning in your fifties are being made under closer supervisory attention, with stress tests and disclosure rules that assume conditions can worsen quickly. Institutions that planned for the benign case are adjusting in public, which is uncomfortable and healthy in equal measure.
What Happens Next
What happens next with earlier retirement planning in your fifties will be visible first in the data that professionals watch weekly: flows, spreads and the terms on new deals. Participants who spoke for this article expect a period of adjustment rather than drama, with the biggest effects landing on those who assumed the old conditions were permanent. Planning, as ever, is the cheapest hedge. You can follow related developments in our coverage of finance.
None of this will be settled by a single announcement, study or product launch. The pattern to watch is accumulation: independent confirmations, honest reporting of failures and steady improvement in the underlying numbers. Readers who follow those signals, rather than the loudest claim of the week, will understand this subject better than most of the commentary surrounding it suggests is possible.
