
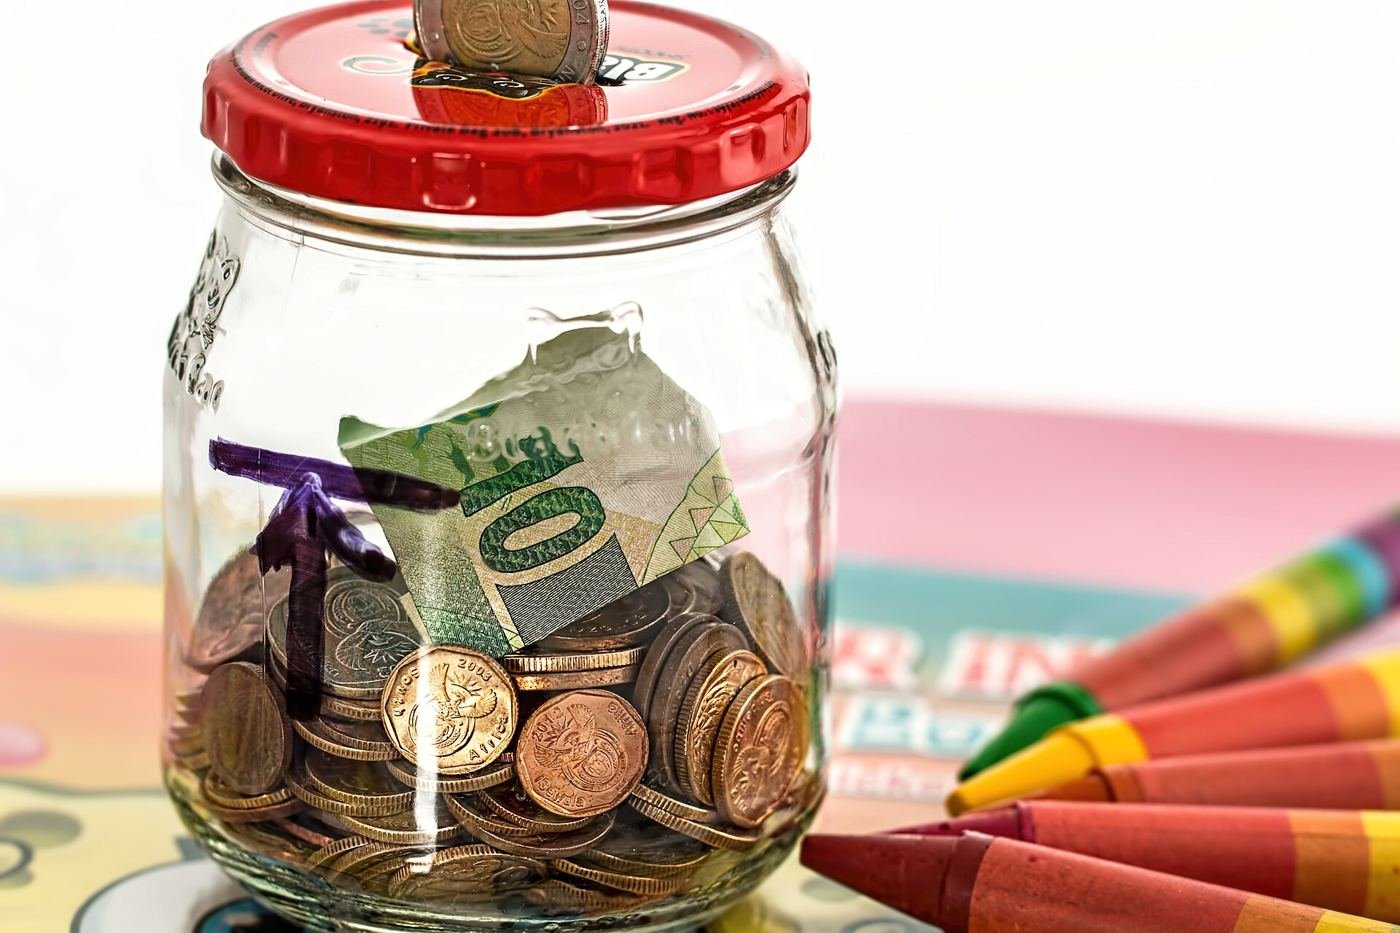
Households are rebuilding savings buffers with simple weekly habits as they try to feel more prepared for repairs, bills and other unexpected costs. Financial advisers say the most effective plans are realistic, automatic and easy to maintain, rather than ambitious targets that collapse after the first difficult month. Moving a small amount on payday, rounding up purchases or pausing one non essential spend each week can slowly create a useful safety cushion. Banks and apps now offer separate savings pots, reminders and progress views that help people see money growing without mixing it with daily spending. The goal for many families is not perfection, but a steady buffer that reduces stress and gives them choices when life becomes unpredictable.
What the Evidence Shows
Starting small also helps people stay motivated, because early progress is visible and the habit feels manageable even when income varies from month to month. Advisers recommend naming each savings pot clearly, whether for emergencies, holidays, school costs or a future deposit, so the purpose stays front of mind. Reviewing regular bills, food waste and energy use can free up modest amounts without making everyday life feel restrictive or joyless for the whole household. When a setback happens, restarting with a smaller amount is better than abandoning the plan entirely and losing the routine that was building confidence. Over several months, consistent habits can turn loose change and careful choices into a reserve that genuinely supports financial security. Reporting and analysis from sources such as Financial Times track the same developments, and specialists following simple weekly habits rebuild savings say the direction is now consistent across independent lines of evidence.
The Wider Context
The wider context is a financial system repricing risk after a long era of cheap money. Decisions shaped by simple weekly habits rebuild savings are being made under closer supervisory attention, with stress tests and disclosure rules that assume conditions can worsen quickly. Institutions that planned for the benign case are adjusting in public, which is uncomfortable and healthy in equal measure.
What Happens Next
What happens next with simple weekly habits rebuild savings will be visible first in the data that professionals watch weekly: flows, spreads and the terms on new deals. Participants who spoke for this article expect a period of adjustment rather than drama, with the biggest effects landing on those who assumed the old conditions were permanent. Planning, as ever, is the cheapest hedge. You can follow related developments in our coverage of finance.
None of this will be settled by a single announcement, study or product launch. The pattern to watch is accumulation: independent confirmations, honest reporting of failures and steady improvement in the underlying numbers. Readers who follow those signals, rather than the loudest claim of the week, will understand this subject better than most of the commentary surrounding it suggests is possible.
