
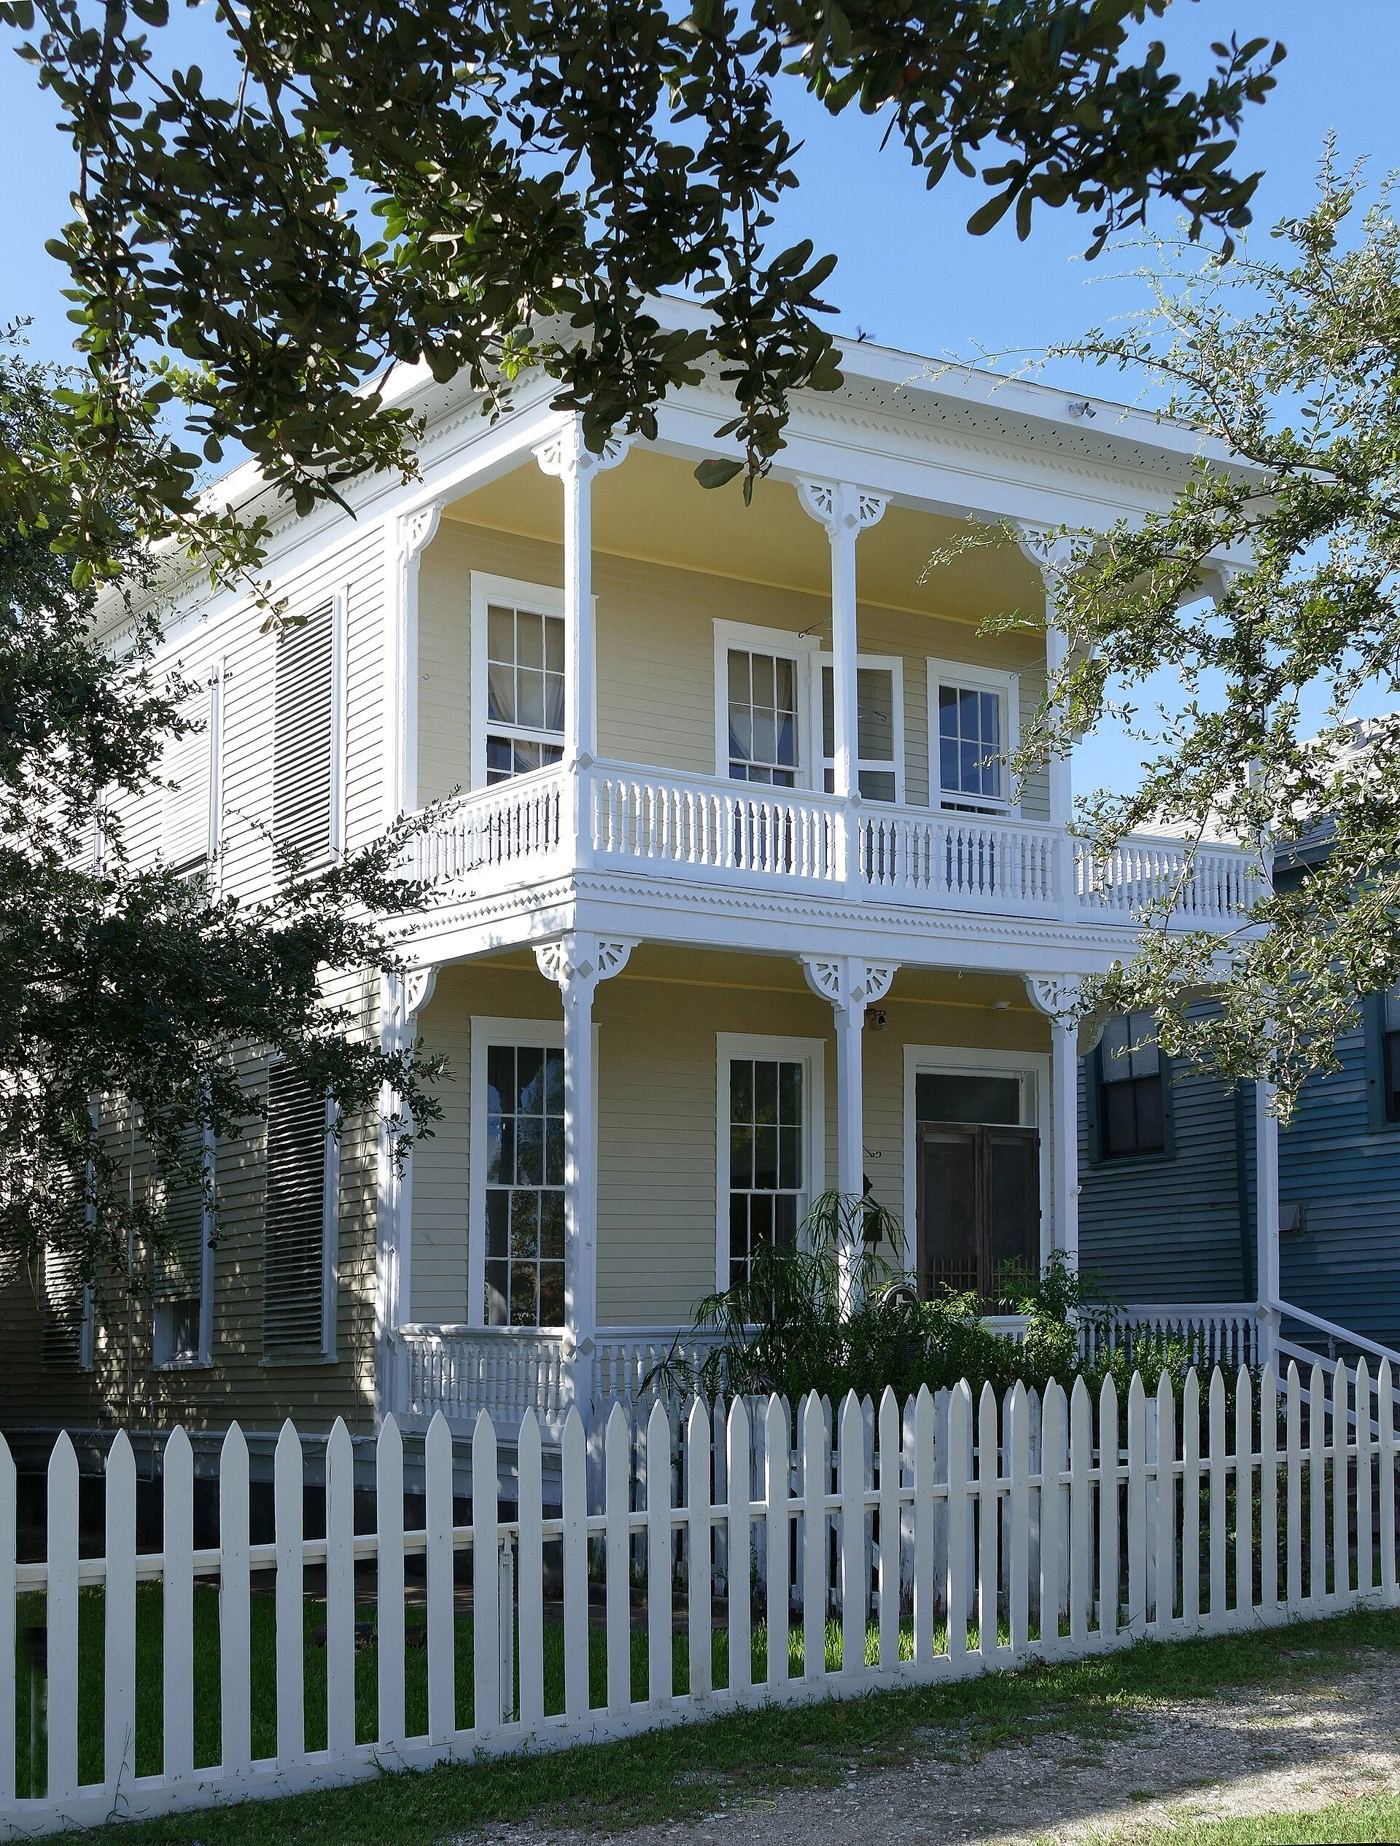
Buying a first home is the largest purchase most people ever make, and the checks carried out before an offer can save thousands. A viewing is only the beginning, because fresh paint and careful staging can hide damp, poor insulation, noisy neighbours and expensive repairs. Experienced advisers suggest visiting the property more than once, at different times of day, to see how light, traffic and noise change. Buyers should ask about the age of the roof, boiler and wiring, check water pressure, look for signs of damp around windows and ceilings, and test doors, taps and sockets. The surrounding streets matter as much as the house itself, including transport links, schools, shops and any planned developments that could change the area. A survey from a qualified professional provides an independent view of the structure and can reveal problems that no viewing would show. Although surveys cost money upfront, they often pay for themselves by giving buyers evidence to renegotiate the price or walk away from a bad deal.
What the Evidence Shows
Financial checks run alongside the physical ones. Buyers need a clear picture of the total cost, including the deposit, mortgage fees, legal costs, stamp duty where it applies, and moving expenses, rather than the headline price alone. A mortgage agreement in principle shows what a lender is willing to offer and strengthens the buyer’s position with sellers. Legal searches reveal planning permissions, flood risk, boundaries and any restrictions on the property, so a good conveyancer is worth the fee. It also helps to budget for the first year of ownership, when repairs and furnishing often arrive together. First-time buyers who rush can end up stretched thin, while those who prepare carefully enter ownership with a buffer for surprises. Taking time, asking questions and accepting professional help are not signs of caution, they are the habits that turn an exciting purchase into a sound one. Reporting and analysis from sources such as World Bank track the same developments, and specialists following first-time home buyer checks say the direction is now consistent across independent lines of evidence.
The Wider Context
For households and small firms, first-time home buyer checks matters through prices and access rather than through market commentary. Changes at this level arrive as a rate on an offer letter, a fee on a statement or a product that quietly disappears from a comparison table. Consumer groups argue that transparency at exactly that point of decision is worth more than any amount of market-level reporting.
What Happens Next
The outlook for first-time home buyer checks hinges on policy choices that will be made in the open over the coming quarters. Market participants are positioned for more than one outcome, which is why the immediate reaction to each announcement has been smaller than the commentary around it. For ordinary savers and borrowers, the advice from every quarter is the same: review your own position, not the headlines. You can follow related developments in our coverage of finance.
It is also worth remembering how quickly the picture in this area has changed before. Positions that looked settled a few years ago have been revised as new data arrived, and the same humility is appropriate now. The strongest coverage of this subject, and the most useful advice, tends to come from sources that update their views openly when the facts move, rather than defending an earlier position long after it has stopped fitting the evidence available.
