
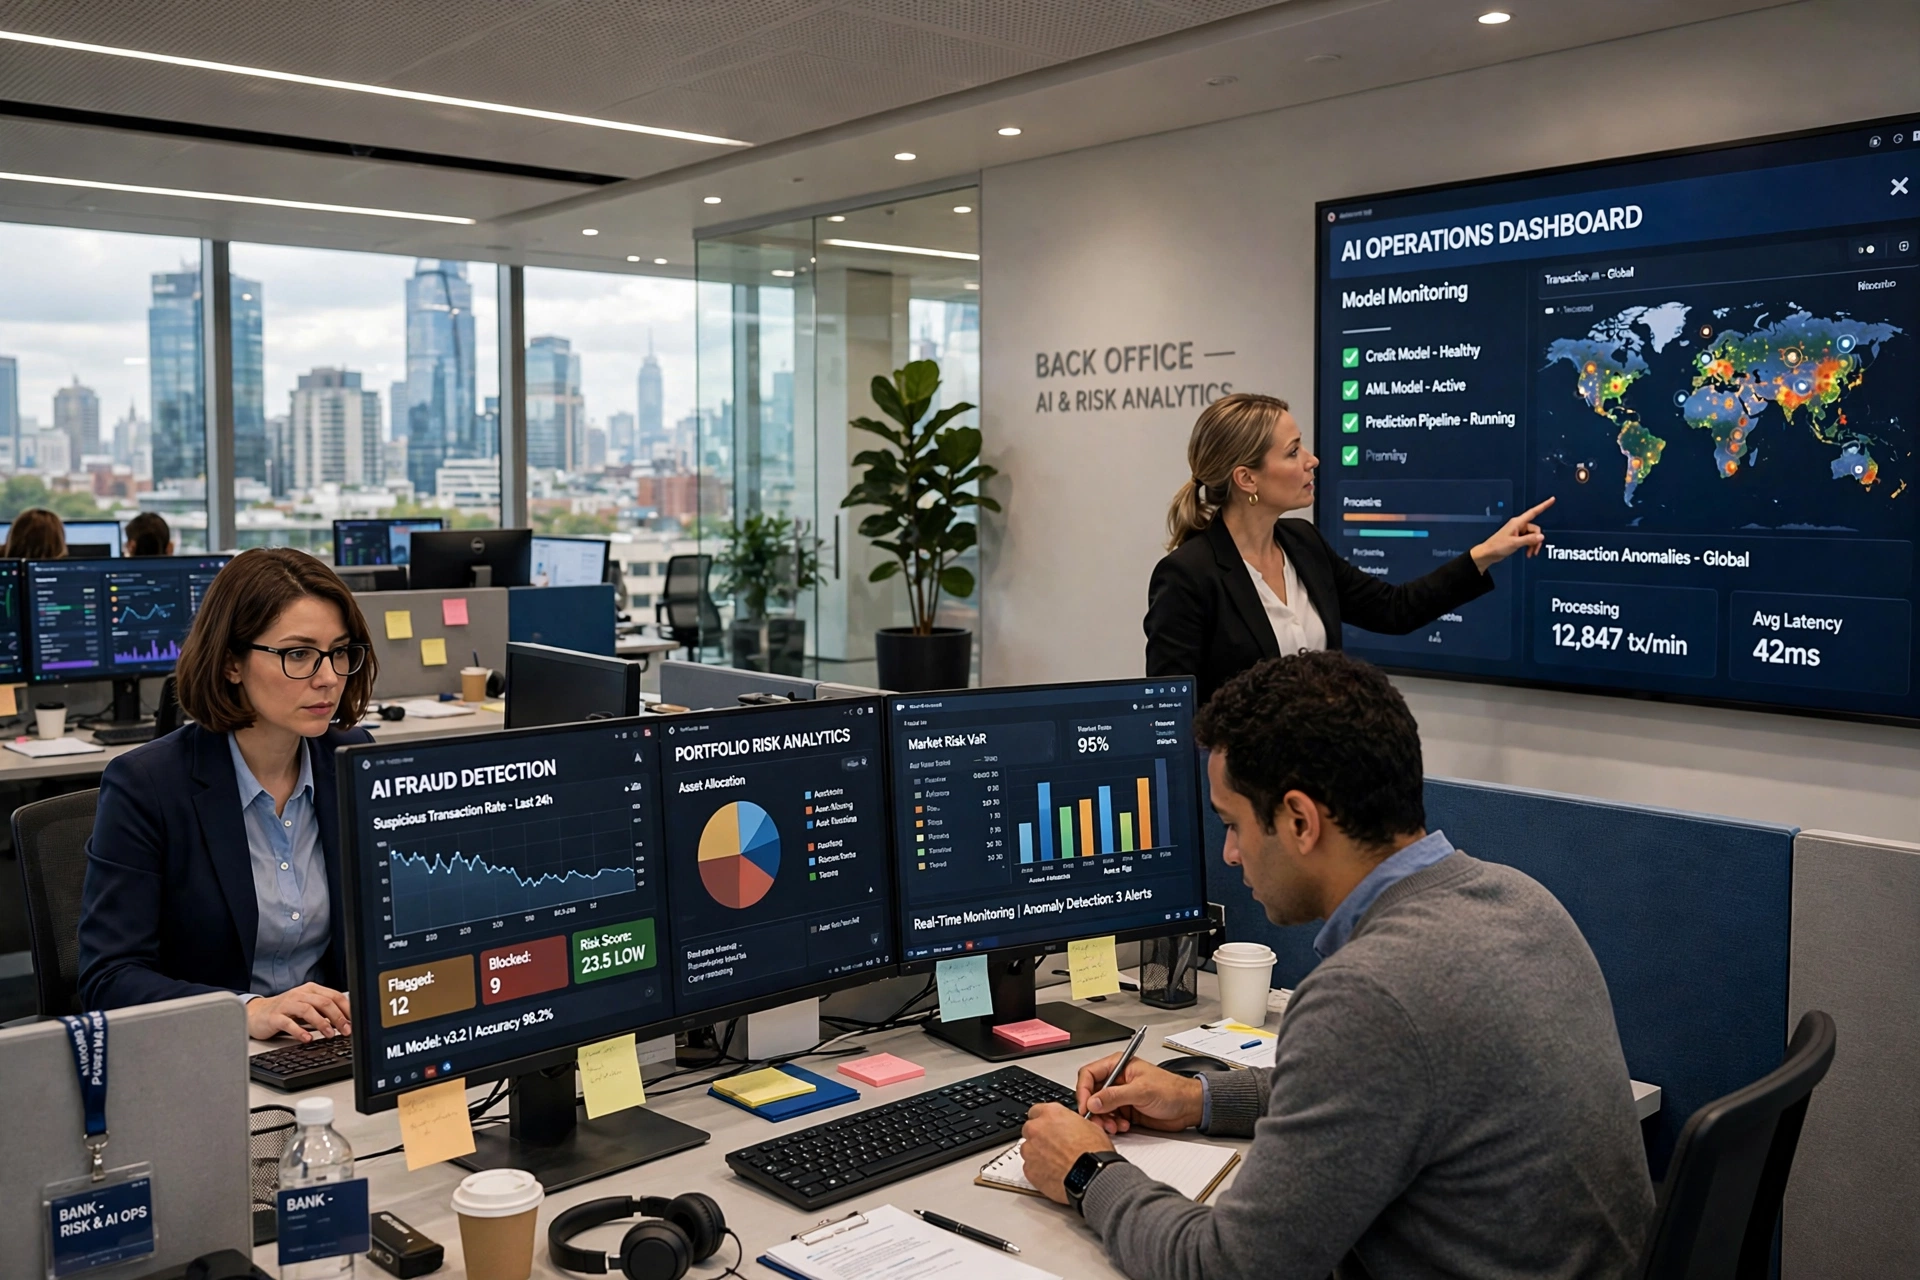
Banks have heard grand promises about artificial intelligence for years, but a new assessment from Boston Consulting Group puts a striking figure on the opportunity: AI could free up around 40 per cent of back-office capacity in banking. That number deserves careful reading. It describes capacity — hours currently absorbed by processing, checking, reconciling and documenting — rather than a forecast that four in ten jobs will disappear. Used well, the prize is not a smaller workforce but a different one, with people moved towards judgement, client relationships and exception handling that machines still do badly.
Where the capacity is hiding
Much of a bank’s back office runs on documents and repetition: onboarding files, payment investigations, loan processing, regulatory reports and the endless reconciliation of systems that were never designed to talk to each other. These are precisely the tasks where modern AI performs best, reading unstructured documents, drafting summaries, flagging anomalies and preparing work for a human decision. BCG’s estimate, discussed at Boston Consulting Group, reflects how much of that workload is rule-based enough to automate in part, even in a heavily regulated industry where final accountability must remain human.
Capacity is not the same as headcount
The distinction matters for staff, customers and policymakers alike. Freeing capacity means the same team can handle more work, clear backlogs faster or spend longer on the cases that genuinely need experience. Banks facing rising transaction volumes and heavier compliance demands may treat AI as a way to absorb growth without equivalent hiring, rather than as an axe. Redeployment, however, is not automatic: it requires retraining, redesigned roles and honest planning about which tasks are shrinking. Institutions that skip that work will struggle to bank the benefit, whatever the technology promises.
What our earlier reporting shows
The capacity question connects directly to the wider economics of the AI build-out, a theme explored in our analysis of the AI spending boom and its infrastructure maths. Banks are simultaneously buyers of AI, financiers of the data centres behind it and institutions whose own operations it may reshape. That triple exposure makes the sector a useful test case: if AI cannot produce measurable productivity in document-heavy banking operations, claims made for other industries will face harder questions; if it can, the template will travel quickly.
The risks executives must price in
Automation in banking carries obligations that a chatbot launch in retail does not. Models must be explainable to regulators, errors in payments or credit files carry real-world harm, and data confidentiality is non-negotiable. BCG’s framing is therefore best read as an upper bound on what is technically releasable, not a savings target to announce before controls are built. Prudent banks will sequence the work: start with low-risk drafting and search, keep humans signing off decisions, audit outputs continuously, and measure released hours honestly rather than assuming every automated minute becomes productive time elsewhere in the business.
The 40 per cent figure will be quoted loosely in the months ahead, usually as a jobs warning. The more useful reading is as a management challenge: banks that treat released capacity as a resource to redeploy — into service, risk judgment and growth — will gain most from AI, while those that see only a cost line to cut may find they have automated away the experience their customers still need.
What success would actually look like
Success, on BCG’s logic, would not appear first as a dramatic cost announcement. It would show up in shorter queues for account opening, fewer errors in payment processing, faster responses to regulators and staff who end the week having handled the difficult cases rather than the routine ones. Those operational gains compound quietly, and they are measurable, which gives boards a better way to judge AI programmes than vendor promises. It also gives employees a fairer story to hear: that the point of the investment is to remove the work nobody values, and to make the work that remains more skilled, better supported and, ultimately, more secure.

1 Comment
Pingback: Dutch Disease explained: how a resource boom lifts the.