

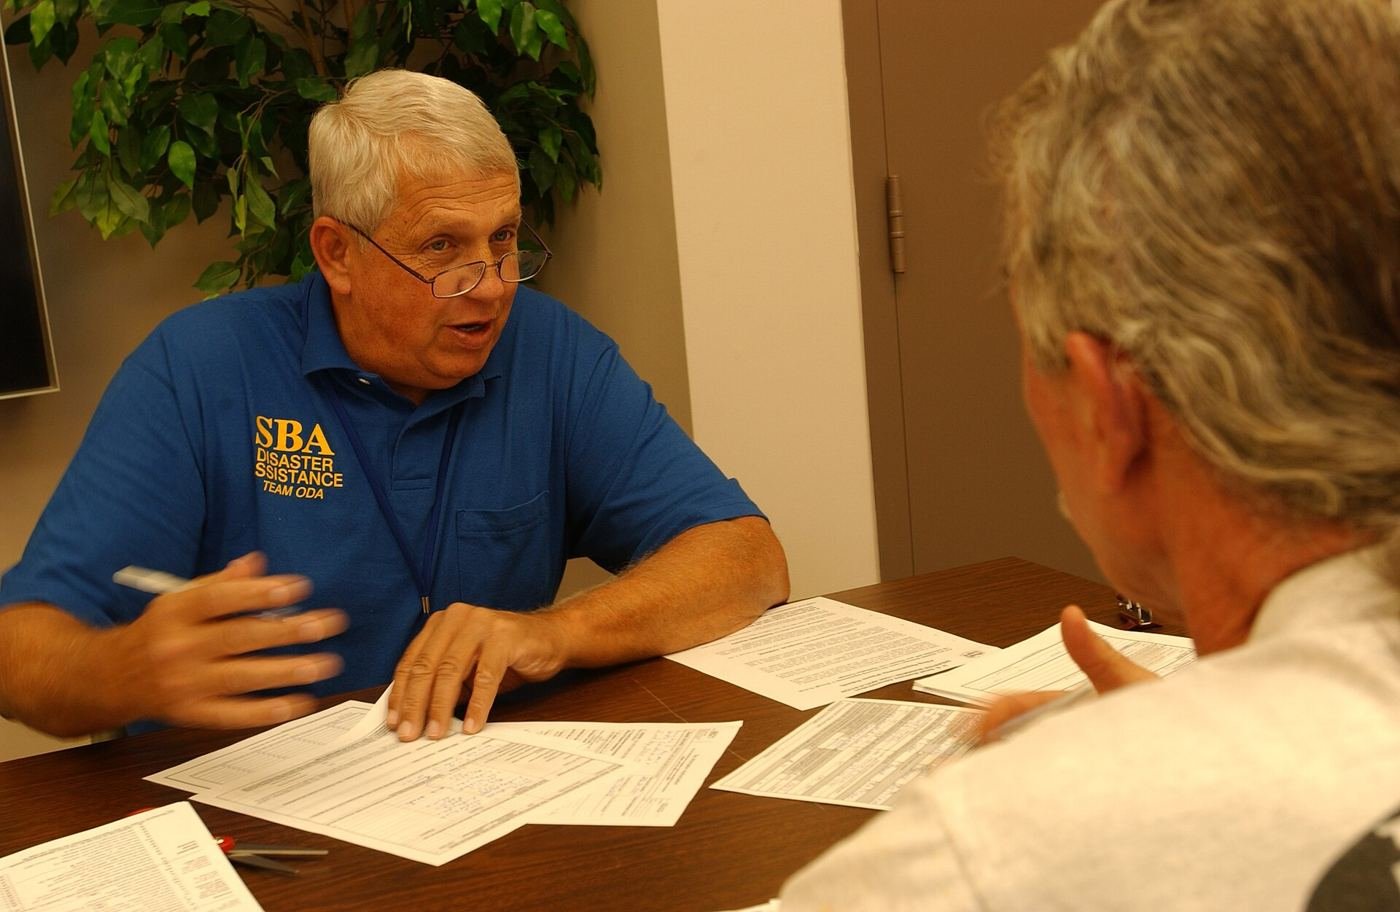
Small businesses often wait thirty, sixty or even ninety days to be paid, and that long wait can leave a healthy firm short of cash for wages, rent and stock. Invoice factoring offers a way out: the business sells its unpaid invoices to a finance company, which pays most of the value immediately and collects the money from the customer later. The firm typically receives around eighty to ninety percent of the invoice within a day or two, with the remainder paid once the customer settles, minus a small fee. For a supplier whose biggest client pays slowly, the arrangement turns a pile of paper into working cash without taking on a loan. The factor checks the creditworthiness of the customers rather than the small business itself, which helps young firms with thin trading histories. Costs vary, usually a percentage of each invoice plus a service charge, so the total price depends on how quickly customers pay. Used carefully, factoring keeps the shelves stocked and the staff paid while the invoices work their way through the system.
What the Evidence Shows
Before signing up, a careful owner weighs the costs against the alternatives. Factoring is usually more expensive than a bank overdraft, so it suits firms that need cash fast rather than those that can wait for payment. The relationship with customers deserves thought too, since some factoring arrangements mean the finance company contacts the customer directly, and a discreet service may be worth paying extra for. Contracts vary, with some requiring the business to factor every invoice and others allowing it to pick and choose. Owners should compare several factors, checking the advance rate, the fees and the minimum monthly volume, since the headline rate rarely tells the whole story. A good factor also chases late payments professionally, which can improve a small firm’s collection habits. For businesses that grow faster than their customers pay, factoring can be the bridge that keeps growth from becoming a cash crisis. Reporting and analysis from sources such as World Bank track the same developments, and specialists following invoice factoring say the direction is now consistent across independent lines of evidence.
The Wider Context
For households and small firms, invoice factoring matters through prices and access rather than through market commentary. Changes at this level arrive as a rate on an offer letter, a fee on a statement or a product that quietly disappears from a comparison table. Consumer groups argue that transparency at exactly that point of decision is worth more than any amount of market-level reporting.
What Happens Next
The outlook for invoice factoring hinges on policy choices that will be made in the open over the coming quarters. Market participants are positioned for more than one outcome, which is why the immediate reaction to each announcement has been smaller than the commentary around it. For ordinary savers and borrowers, the advice from every quarter is the same: review your own position, not the headlines. You can follow related developments in our coverage of finance.
It is also worth remembering how quickly the picture in this area has changed before. Positions that looked settled a few years ago have been revised as new data arrived, and the same humility is appropriate now. The strongest coverage of this subject, and the most useful advice, tends to come from sources that update their views openly when the facts move, rather than defending an earlier position long after it has stopped fitting the evidence available.
