

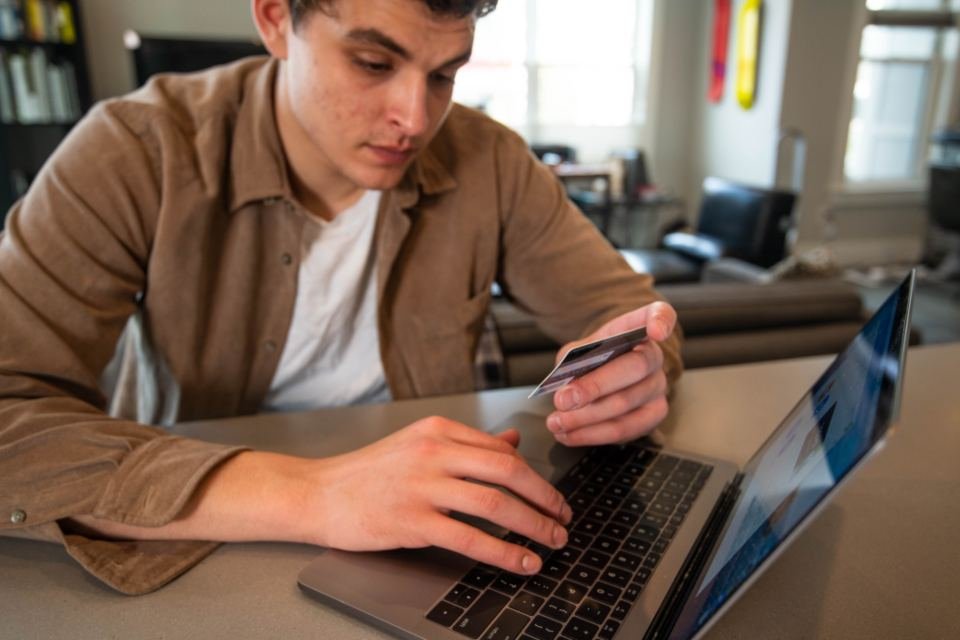
Business credit cards have become a fixture in the wallets of small firms, promising cashback, travel points and a month of interest-free credit on every purchase. The appeal is obvious: a company that spends heavily on supplies, fuel or advertising can earn hundreds back each year simply by paying with the card instead of a bank transfer. Many cards add practical extras, such as spending limits for each employee, itemised statements that simplify bookkeeping and integration with accounting software. The interest-free period, usually around a month, lets a firm buy stock now and pay after the goods have been sold. Yet the same card that rewards careful spending can punish careless use, with interest rates that are often far higher than a bank loan. Annual fees vary widely, from free cards with modest rewards to premium cards that charge several hundred a year for airport lounges and insurance. For a disciplined business, the card is a useful tool; for one that carries a balance, it quickly becomes an expensive habit.
What the Evidence Shows
Picking the right card means matching it honestly to how the business actually spends. A firm that buys most of its stock from one supplier should look for a card that rewards that category, while one whose staff travel often may value points that convert into flights. The annual fee is only worth paying when the rewards clearly exceed it, so owners should add up a year’s spending before choosing. Paying the balance in full every month is the golden rule, since interest charges wipe out cashback many times over. Owners should also check who is liable for the debt, because some cards hold the business alone responsible while others put the director’s personal assets on the line. Employee cards need clear limits and a simple expenses policy to prevent surprises. Compared side by side, the best card is rarely the one with the biggest headline reward, but the one that fits the firm’s real spending and is paid off on time. Reporting and analysis from sources such as Financial Times track the same developments, and specialists following business credit cards say the direction is now consistent across independent lines of evidence.
The Wider Context
The wider context is a financial system repricing risk after a long era of cheap money. Decisions shaped by business credit cards are being made under closer supervisory attention, with stress tests and disclosure rules that assume conditions can worsen quickly. Institutions that planned for the benign case are adjusting in public, which is uncomfortable and healthy in equal measure.
What Happens Next
What happens next with business credit cards will be visible first in the data that professionals watch weekly: flows, spreads and the terms on new deals. Participants who spoke for this article expect a period of adjustment rather than drama, with the biggest effects landing on those who assumed the old conditions were permanent. Planning, as ever, is the cheapest hedge. You can follow related developments in our coverage of finance.
None of this will be settled by a single announcement, study or product launch. The pattern to watch is accumulation: independent confirmations, honest reporting of failures and steady improvement in the underlying numbers. Readers who follow those signals, rather than the loudest claim of the week, will understand this subject better than most of the commentary surrounding it suggests is possible.
