Close Menu
Weekly Business Records
    Facebook X (Twitter) Instagram
    Weekly Business RecordsWeekly Business Records
    • Home
    • Business
    • Finance
    • Insights
    • Reports
    • Security
    Weekly Business Records
    Home»Finance»Small Firms Face a Tighter Credit Squeeze as Lenders Turn Cautious

    Small Firms Face a Tighter Credit Squeeze as Lenders Turn Cautious

    Leon FischerBy Leon FischerOctober 21, 2026No Comments4 Mins Read
    Facebook Twitter Pinterest LinkedIn Tumblr Reddit Telegram Email
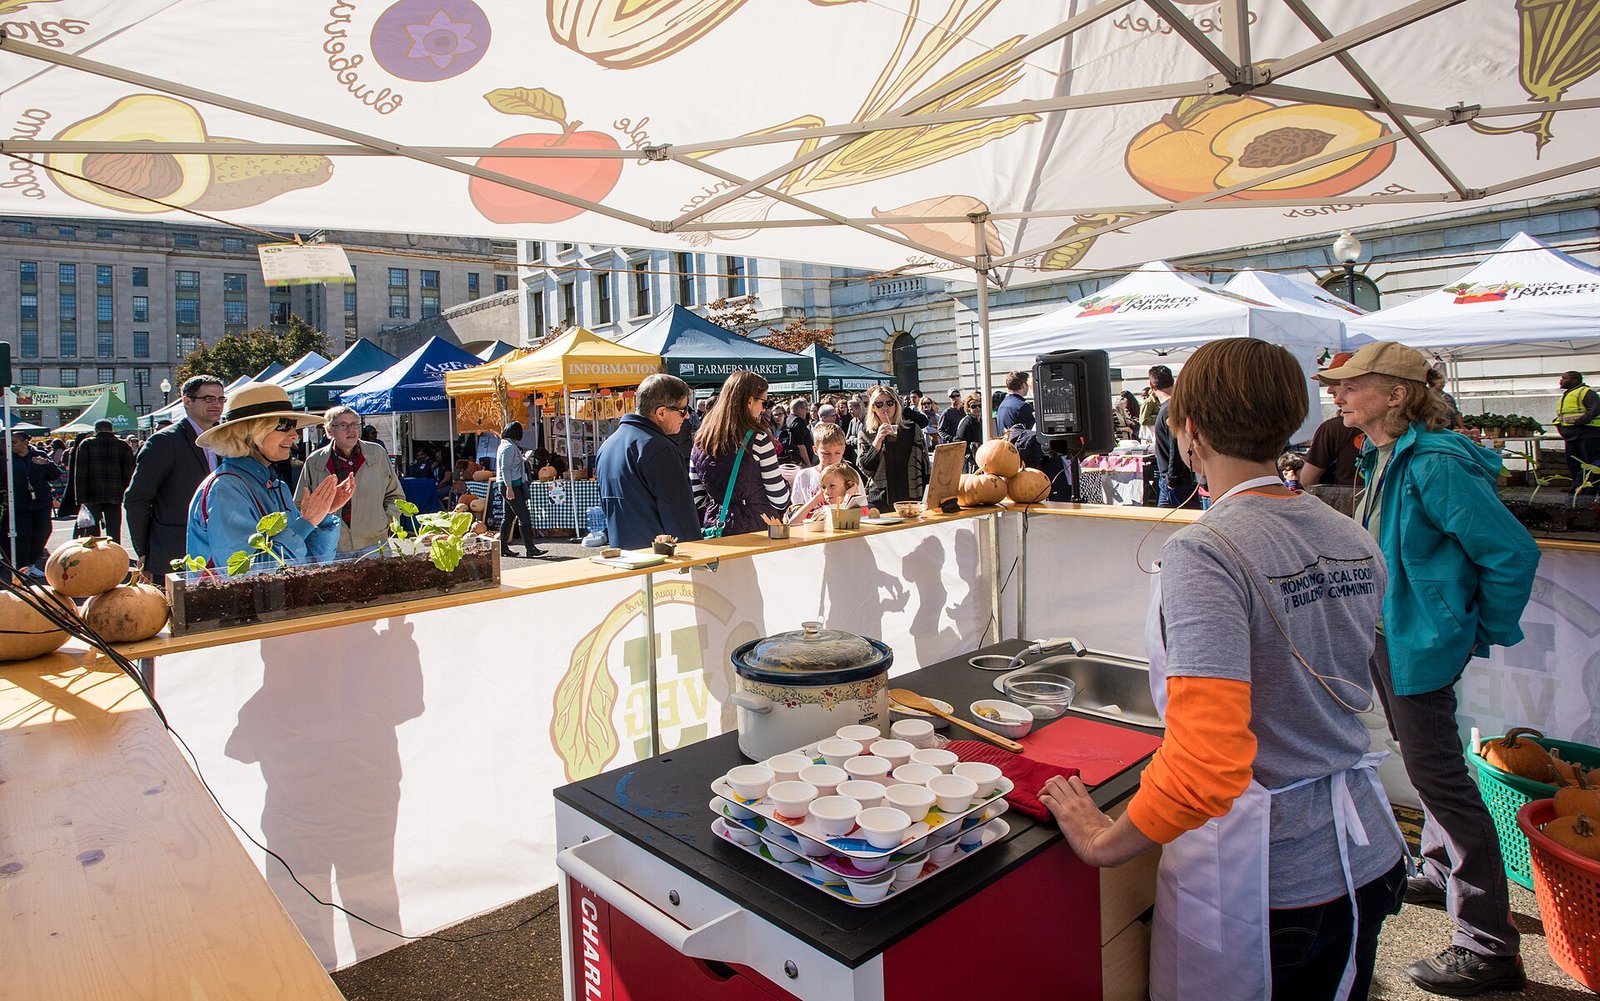
    A small business owner at the counter of their shop
    U.S. Department of Agriculture (USDA) Agricultural Marketing Service (AMS) “VegU” Program Coordinator Laura Popielski at the cooking counter cooking pumpkin curry soup and Janet talking with the audience about how she grew 50 pumpkins in her garden and are now on display with seedlings in the clear planters at the USDA Farmers Market which celebrates the close of its 22nd season on Oct 27, 2017, in Washington, DC. The last market day featured live music from the U.S. Army Band, farm animal exhibits. Visitors were able to bowl with squash, help harvest and learn about sweet potatoes for DC Central Kitchen, pick and paint pumpkins, meet farm animals, shop for fresh picked local produce from the Chesapeake Bay Region, enjoy prepared foods, see live turkeys from Tall Cotton Farm, get a farm animal and veggie-themed temporary tattoo to wear, and shop for food inspired art work. “VegU” Program Coordinators prepared and talk about a pumpkin curry soup recipe during free 10-minute fruit and vegetable classes at the “VegU(cation)” tent where people learned how to how to pick, store, and prepare pumpkin curry soup. Fruits and vegetables are featured during their peak harvest time. The USDA farmers market is located on the corner of 12th Street and Independence Ave, SW; features live music, 30+ farmers, ranchers, and small business owners in the Chesapeake Bay Region. The festival played host to thousands of visitors from around America and looks to open May 4, 2018. For more information visit usda.gov/farmersmarket or follow @USDA_AMS on Twitter and Instagram using hashtag #USDAFarmersMkt. View photos of the market on Flickr. USDA Photo by Lance Cheung. PUMPKIN CURRY SOUP Yields 8 cups Prep Time: 1 hour | Cook Time: 20 minutes | Total Time: 1 hour 20 minutes 1 tbsp. olive oil 1 medium onion, finely chopped 3 garlic cloves, minced 3 lb. fresh sugar pumpkin 3 cups vegetable stock 1 tbsp. curry powder 1 tsp. chili powder Salt and pepper to taste 1. Preheat oven to 350° F. 2. Remove pumpkin stem and slice pumpkin in half using a sharp knife. Remove pumpkin seeds and stringy innards with a spoon. Discard or save seeds to roast later on. 3. Brush pumpkin halves with oil and place face down on a parchment-lined baking sheet. Bake for 45 minutes or until tender. 4. Remove from oven and let cool. Separate pumpkin flesh from skin. Purée the pumpkin flesh in a blender or food processor. (Process to your preference of a smooth to chunky texture. See photo album for examples.) 5. In a pot, heat onion and garlic over medium heat. Add vegetable stock, puréed pumpkin, curry powder and chili powder. 6. Bring soup to a boil then reduce heat and simmer for 10 minutes. Note: Each pound of sugar pumpkin should yield 1 cup of pumpkin purée. Adapted from © My Darling Vegan 2016 THIS WEEK VEGU IS ALL ABOUT PUMPKINS Three different species in the Curburita genus are known as pumpkins (Cucurbita pepo, C. maxima, C. moschata). Pumpkins are typically planted in early summer and harvested in fall. Pumpkins can be stored for several months after harvesting due to their thick outer skin. There are countless different varieties of pumpkins grown in the United States ranging in size from 2 pounds to 100 pounds and in an array of colors including orange, yellow, green, and white. One of the most common pumpkin varieties used for cooking and baking is Sugar Pie (also known as pie pumpkins), which has thin skin and sweet flesh making it ideal for eating. HOW TO PICK Look at size. Choose pumpkins that feel solid and heavy for their size. Check for blemishes. Pick pumpkins that are unblemished, have consistent color and have the stems attached. Feel for freshness. Press on the bottom of the pumpkin. If it is flexible or has several soft spots it may indicate that it is not as fresh. HOW TO PREPARE To cook a fresh pumpkin, first wash and dry the whole pumpkin. Remove the stem and slice the pumpkin in half using a sharp knife. Clean out the inside, removing the seeds and fibrous strings. Place the halves on a cookie sheet or tray and bake at 350º F for about 30-45 minutes depending on the size. Once cooled, peel off the skin using a knife and chop the pumpkin into cubes, or purée the flesh in a blender or food processor. Use cooked pumpkin purée or cubes in pies, cakes, baked goods, soups, and stews. HOW TO STORE Pumpkins require cool and dry conditions for best storage. Optimal temperature is between 50-55º F and humidity of 50-70%. If stored properly, certain varieties of pumpkin can last up to two months. Tip: Store cooked, cubed or puréed pumpkin for up to one week in the refrigerator. Advice about freezing. Freezing pumpkin is a great option. To freeze, first roast pumpkin in the oven (as outlined on the other side of this handout) and place cooked cubes or puréed pumpkin into freezer bags. To freeze raw cubes, first peel the pumpkin skin and remove seeds and fibrous strings. Chop pumpkin into 1-inch cubes and store loosely in freezer bags. Frozen pumpkin can be stored for 9 months to 1 year. FUN FACTS • Pumpkins originated in Central America and are botanically a fruit. • At the first Thanksgiving feast in 1621, the pilgrims did not serve pumpkin pie, rather, they served stewed pumpkin. • Pumpkins are members of the Cucurbitaceae family, which includes squash, zucchini, watermelon, cucumbers and gourds. • Over 50,000 acres of pumpkins were harvested in the United States in 2014, producing 1.3 billion pounds of pumpkins. • China and India are the world’s top pumpkin producers; U.S. is ranked fifth. • Illinois is the top pumpkin producing state in the U.S. followed by California, Ohio and Pennsylvania. • Pumpkin is an excellent source of beta-carotene, the precursor to vitamin A. • 99% of pumpkins grown in the U.S. are sold for decoration.

    For many small companies, the hardest conversation in business has become the one at the bank. Loan officers who once approved a working-capital line in a fortnight now ask for three years of audited accounts, personal guarantees and property as security, and still take two months to answer. Surveys of small-business sentiment in Britain, the eurozone and the United States tell the same story from different angles: credit is available, but on terms that steadily fewer owners can accept.

    The squeeze is not a crisis of the kind seen in 2008. Banks are well capitalised and, by their own account, open for business. What has changed is the price of risk. Higher interest rates have raised the cost of every default, a run of insolvencies in retail and hospitality has made lenders wary of entire sectors, and regulators continue to press banks to hold more capital against small, unrated borrowers. The result is a quiet rationing that rarely makes headlines but shows up in postponed hires, cancelled equipment orders and shelves stocked a little thinner than they should be. Readers can follow more coverage like this on weeklybusinessrecords.com.

    Why Lenders Are Pulling Back

    Part of the shift is arithmetic. When base rates sat near zero, a lender could absorb a handful of bad small-business loans and still profit from the portfolio. At today’s rates, the margin for error is thinner, and credit models respond by demanding more evidence of steady cash flow. Firms with lumpy, seasonal income — builders, events companies, independent retailers — score badly in those models even when their order books are healthy, because the models reward predictability over profitability.

    There is also a structural change in who lends. The big banks have steadily retreated from the smallest end of the market, where a £40,000 loan costs almost as much to assess as a £4 million one. Challenger banks and specialist lenders have filled some of the gap, but their funding costs are higher, and their rates show it. Owners who once compared two bank offers now compare a bank against an invoice-finance broker, a merchant cash advance and, increasingly, the option of simply not borrowing at all.

    What the Squeeze Costs on the Ground

    The costs are easy to miss in aggregate statistics because they take the form of things that do not happen. The café that does not open a second site. The manufacturer that runs a twenty-year-old machine for another year rather than financing its replacement. Economists call this the investment gap, and it compounds: a business that under-invests for three consecutive years rarely catches up, because competitors with better access to finance have meanwhile bought the faster machine, the better location and the stronger team. Further data and analysis on this subject are available from the British Business Bank.

    Cash-flow pressure also changes behaviour inside firms. Owners stretch payments to suppliers, which pushes the squeeze down the chain to even smaller businesses. Late payment, long the bane of small firms, tends to worsen exactly when credit tightens, creating a feedback loop in which everyone’s working capital deteriorates at once. Accountants report that the first sign of trouble is rarely a refused loan; it is a directors’ loan quietly funding the wage bill, a step that turns a business problem into a personal one.

    How Owners Are Adapting

    The firms coping best have changed how they present themselves to lenders. Clean, monthly management accounts — once a luxury — are now close to a requirement, and owners who can show a lender twelve months of tidy numbers, a sensible forecast and a clear purpose for the money report markedly better outcomes. Brokers say preparation has become the single biggest difference between an approval and a refusal, ahead of the trading record itself.

    Others are diversifying their funding before they need it: an overdraft for flexibility, asset finance for equipment, and community lenders or credit unions for smaller sums. The lesson veterans repeat is to arrange credit while the sun shines, because facilities negotiated from strength are cheaper and larger than those begged for in a crisis. As one adviser puts it, the best time to meet your bank manager is when you do not need anything at all. See also our companion piece: Bond Markets Bet on Rate Cuts, but Central Bankers Urge Patience.

    Credit finance Lending small business
    Leon Fischer

    Related Posts

    Bond Markets Bet on Rate Cuts, but Central Bankers Urge Patience

    October 21, 2026

    Profitable but Broke? The Cash Flow Trap Explained

    October 20, 2026

    A Beginner’s Guide to Index Funds and Long-Term Wealth

    October 20, 2026
    Leave A Reply Cancel Reply

    Search
    Recent Posts

    Small Firms Face a Tighter Credit Squeeze as Lenders Turn Cautious

    October 21, 2026

    Bond Markets Bet on Rate Cuts, but Central Bankers Urge Patience

    October 21, 2026

    Profitable but Broke? The Cash Flow Trap Explained

    October 20, 2026

    A Beginner’s Guide to Index Funds and Long-Term Wealth

    October 20, 2026

    Why CFOs Say AI Projects Are Not Paying Off Yet

    October 19, 2026

    5 Smart Financial Moves to Consider in Your 60s

    October 19, 2026

    Understanding Promotions and Offers: Reading Offer Terms Before Participating

    October 18, 2026

    Why Bond Yields Matter More Than the Headlines: The Quiet Market That Sets Borrowing Costs

    October 18, 2026
    Categories
    • Blog
    • Business
    • Finance
    • Insights
    • Reports
    • Security
    About Us

    Weekly Business Records Smart Tracking Smart Business. Track weekly data, boost efficiency, improve organization, streamline

    operations, drive decisions, grow business faster with powerful, organized insights tailored for smarter business moves.

    Facebook X (Twitter) Pinterest YouTube WhatsApp
    Popular Posts

    Small Firms Face a Tighter Credit Squeeze as Lenders Turn Cautious

    October 21, 2026

    Bond Markets Bet on Rate Cuts, but Central Bankers Urge Patience

    October 21, 2026

    Profitable but Broke? The Cash Flow Trap Explained

    October 20, 2026
    Contact Us

    We’d love to hear from you at Weekly Business Records! Whether you’ve got a news tip, ad inquiry, or need assistance, don’t hesitate to get in touch.

    Email: contact@outreachmedia .io
    Phone: +92 305 5631208

    Address:1358 Marie Street
    Baltimore, MD 21218


    หวยออนไลน์

    Copyright © 2026 | All Right Reserved | Weekly Business Records

    • About Us
    • Contact Us
    • Disclaimer
    • Privacy Policy
    • Terms and Conditions
    • Write For Us
    • Sitemap

    Type above and press Enter to search. Press Esc to cancel.

    WhatsApp us