
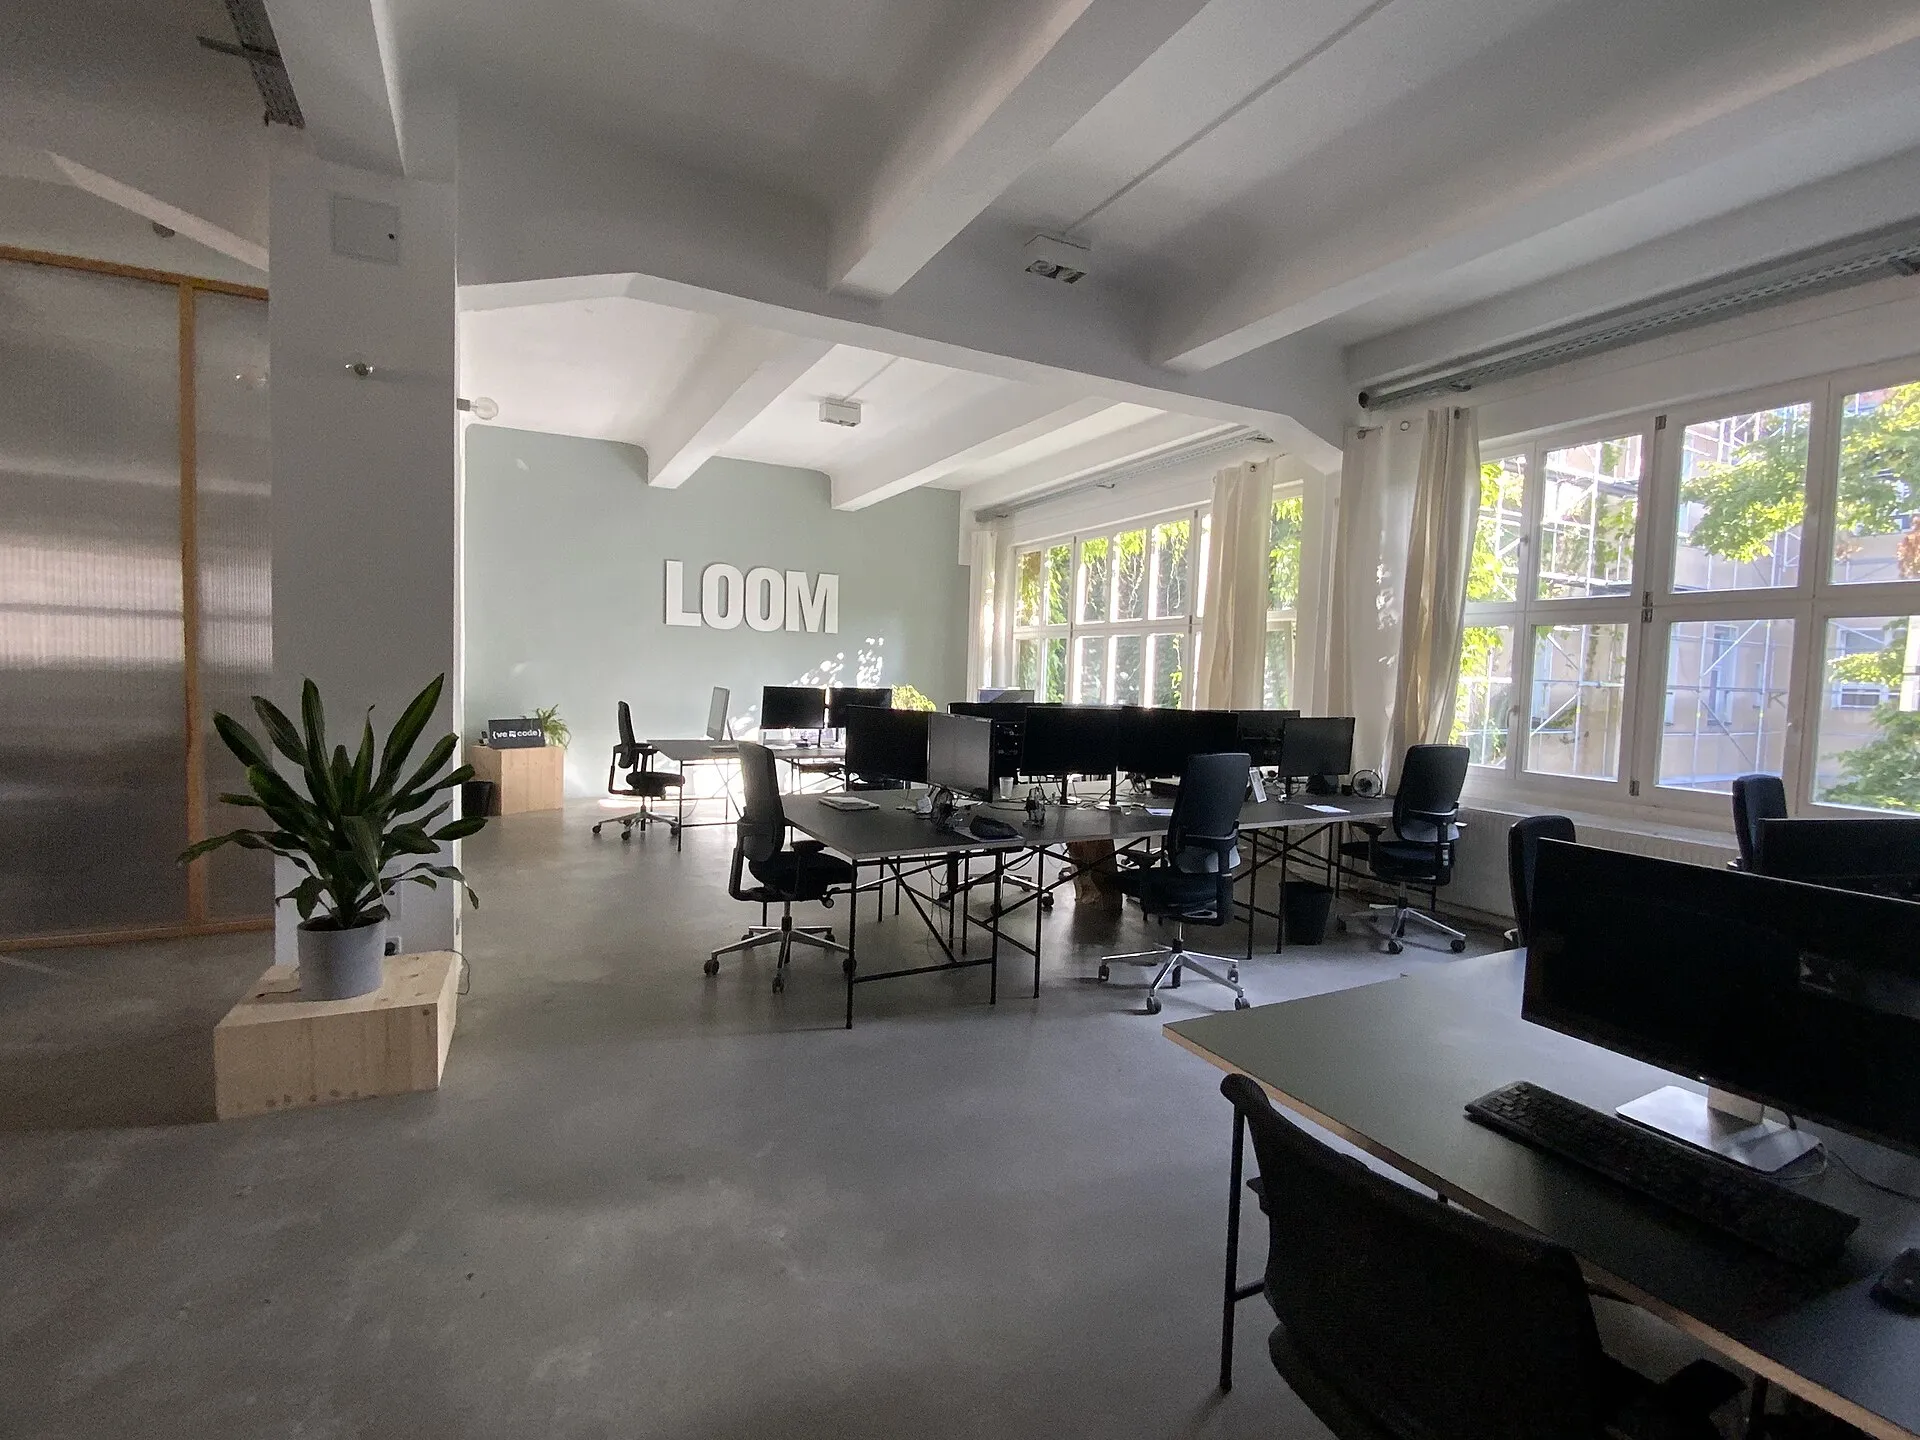
Walk through almost any major business district on a Friday and the change is impossible to miss: quieter lifts, darker windows, sandwich bars that once queued out of the door now trading at a stroll. Hybrid working has settled into a durable pattern, and it has left a question hanging over the world’s office towers that the business press returns to again and again. If the office is no longer the default place of work, what happens to the buildings, the landlords, the lenders behind them — and the city centres built around all three?
This is not an argument that the office is dead. It is an argument about quantity. Many companies have concluded they need less space than before, arranged differently, in better locations. That shift, multiplied across thousands of leases, is what makes the empty office a business story rather than a lifestyle one. Our wider Business coverage follows how companies are adapting to the new pattern of work.
How the office lost its default status
Before 2020, attendance was simply assumed: the office was where work happened, and home was the exception. The pandemic broke that assumption at scale, and the years since have been a long negotiation. Employers who demanded a full return often met resistance, resignations, or both. Employees, having proved their jobs could be done from a kitchen table, treated commuting as a cost that needed justifying. The result in most large economies is a hybrid middle — a few days in, a few days out — that looks less like a temporary compromise and more like a settled arrangement.
Settled arrangements have financial consequences. When leases come up for renewal, finance directors ask why the company is paying for desks that sit empty two days a week. Space is one of the largest costs a business carries, so even a modest reduction per firm becomes, in aggregate, a structural fall in demand for office space — concentrated, awkwardly, in the older buildings that were hardest to fill even before the shift.
The landlord and lender problem
Office buildings are usually bought with borrowed money, on the assumption of steady rent from long leases. Falling demand attacks that model from both sides: rents for mediocre space weaken, and the building’s value — which is essentially capitalised rent — falls with them. Trouble tends to surface at refinancing, when a loan taken out in easier times must be replaced and the building no longer supports the same debt. The Federal Reserve’s Financial Stability Report regularly examines this corner of commercial real estate as a risk worth monitoring for banks.
The honest debate is about scale. Pessimists see a slow-motion version of the shopping mall decline, with losses filtering through to regional banks and pension funds that own property debt. Optimists counter that offices are a smaller, more localised exposure than housing was in 2008, that the best buildings remain full, and that losses will be absorbed over years rather than detonating at once. Both sides can point to real evidence; the difference is how far the weakness spreads beyond ageing stock in weaker locations.
What empty offices do to city centres
An office tower is an economic engine for everything around it. Commuters buy coffee, lunches, dry cleaning, gym memberships and train tickets; take away a slice of that footfall and the businesses depending on it feel the gap. City governments feel it too, through lower commercial tax revenue and emptier public transport at the hours it was designed for. This is why mayors have been among the loudest voices urging a return to the desk — their budgets were built on the old pattern.
Yet the story is not purely one of decline. Residential conversions are turning some obsolete offices into apartments, bringing evening and weekend life to districts that once emptied at six. Leisure, education and healthcare tenants are taking space that firms no longer want. The city centre is being renegotiated rather than abandoned, and the winners look likely to be mixed neighbourhoods rather than single-purpose office zones.
The case for a smaller, better office
Ask property agents where demand is strong and a clear pattern emerges: the newest, greenest, best-located buildings are leasing, often at record rents, while tired stock languishes. Companies cutting space are frequently trading up — fewer desks, but in buildings worth commuting to, with collaboration space replacing rows of workstations. Analysts call it the flight to quality, and it explains the apparent paradox of rent records and vacancy headlines coexisting in the same city. The market is not shrinking uniformly; it is splitting.
Where the debate goes next
The next phase will be decided by arithmetic more than by opinion. As more leases expire, the true level of demand will reveal itself; as loans mature, owners of weak buildings will have to sell, convert or hand back the keys. New supply has already slowed sharply, which eventually supports the survivors. For investors, the lesson of the debate is selectivity: “the office” is no longer one asset class but at least two, moving in opposite directions. For the rest of us, the quieter Friday high street is probably not a phase — it is the visible edge of a permanent change in how, and where, white-collar work gets done. Readers new to the sector can find the key terms defined in Investopedia’s guide to commercial real estate.
